Lietuvių
 Русский
 Қазақша
 Eesti
September 14 – September 20, 2026: Weekly economic update
Key market updates
Key Takeaways:
- The policy rate was raised to a range of 3.75-4.00%; rhetoric turned hawkish;
- Monetary policy remains moderately restrictive;
- U.S. macroeconomic data continue to support a soft-landing scenario: inflation risks are increasing, the labor market is cooling without signs of recession, and current conditions do not yet warrant a rate cut.
- The Fed slightly improved its GDP and employment forecasts; it raised near-term inflation forecasts.
Inflation: Consumer Price Index (August)
- Core CPI (MoM): 0.3% (previous: 0.2%).
- Core CPI (YoY): 2.4% (previous: 2.5%).
- CPI (MoM): 0.4% (previous: 0.1%).
- CPI (YoY): 3.4% (previous: 3.4%).
Producer Price Index (August)
- PPI (MoM): 0.4% (previous: 0.0%).
- Core PPI (MoM): 0.3% (previous: 0.2%).
Inflation Expectations (Michigan) (August)
- 12-month Inflation Expectations: 4.6% (previous: 4.3%).
- 5-Year Inflation Expectations: 3.4% (previous: 3.3%).
GDP (U.S. Bureau of Economic Analysis, BEA) — Q2 2026 annualized growth rate, second estimate: +1.5% (Q1 2026: +2.1%); forecast: 1.5%.
GDPNow (the Atlanta Fed’s real-time estimate of official GDP growth ahead of release (Q3 2026)): 5.1% (previous: 4.4%).
Trade balance (July): -88 bn (-71.2 bn).
Labor Market (BLS) (July/August)
- Unemployment rate 4.1% (prev: 4.1%):
- Total number of people receiving unemployment benefits in the US: 1,774K (prev: 1,779K);
- Initial jobless claims: 196K (prev: 207K);
- Change in nonfarm payrolls: 162K (prev: 23K):
- Change in employment in the private nonfarm sector: 127K (prev: -30K):
- Average hourly earnings (y/y): 3.1% (prev: 3.2%);
- JOLTS job openings: 7.271M (prev: 6.866M).
Business Activity Index (PMI) (July)
(Above 50 indicates expansion; below 50 indicates contraction)
- Services PMI: 56.5 (previous: 56.8).
- Manufacturing PMI: 53.9 (previous: 53.8).
- Composite PMI: 56.0 (previous: 56.0).
Monetary Policy
The FOMC (Federal Open Market Committee) held its meeting. The committee raised the rate by 25 bps.
Chairman Kevin Warsh's main message: the U.S. economy is strengthening, but inflation risks are tilted to the upside, while labor market risks are roughly balanced. Inflation is too high and has stayed that way for too long.
Overall, the tone was noticeably more hawkish than at the previous meeting.
In the forecasts provided, the Committee slightly improved its GDP and employment outlook. Short-term inflation forecasts were raised, long-term forecasts unchanged.
- Federal funds rate (EFFR): 3.75%–4.00%
FOMC forecasts:
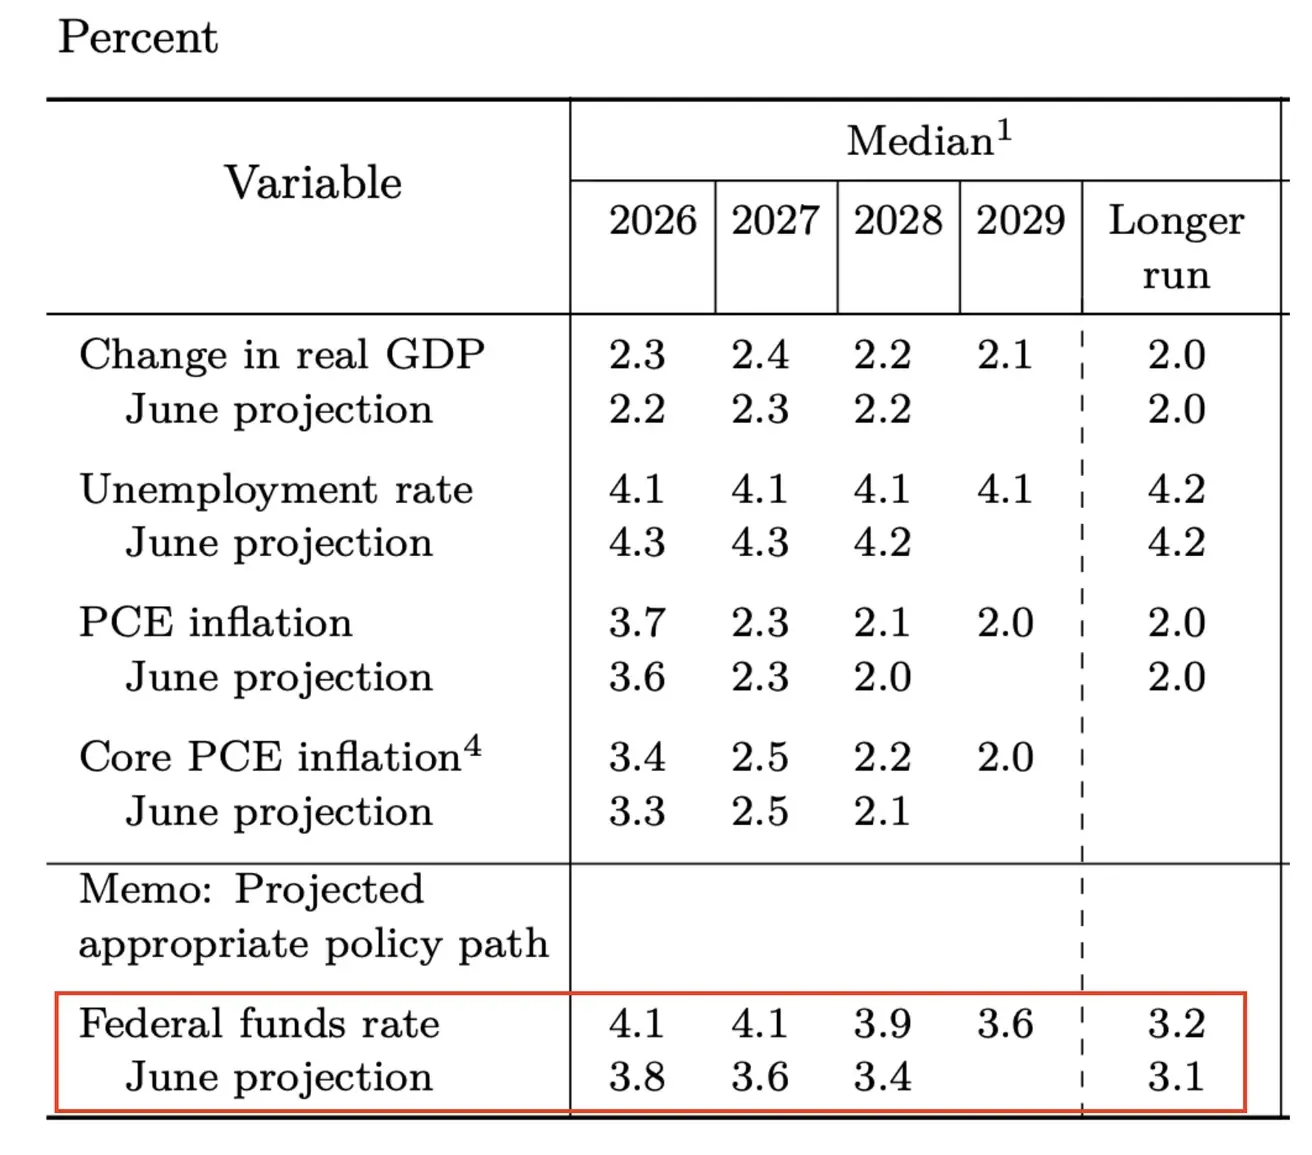
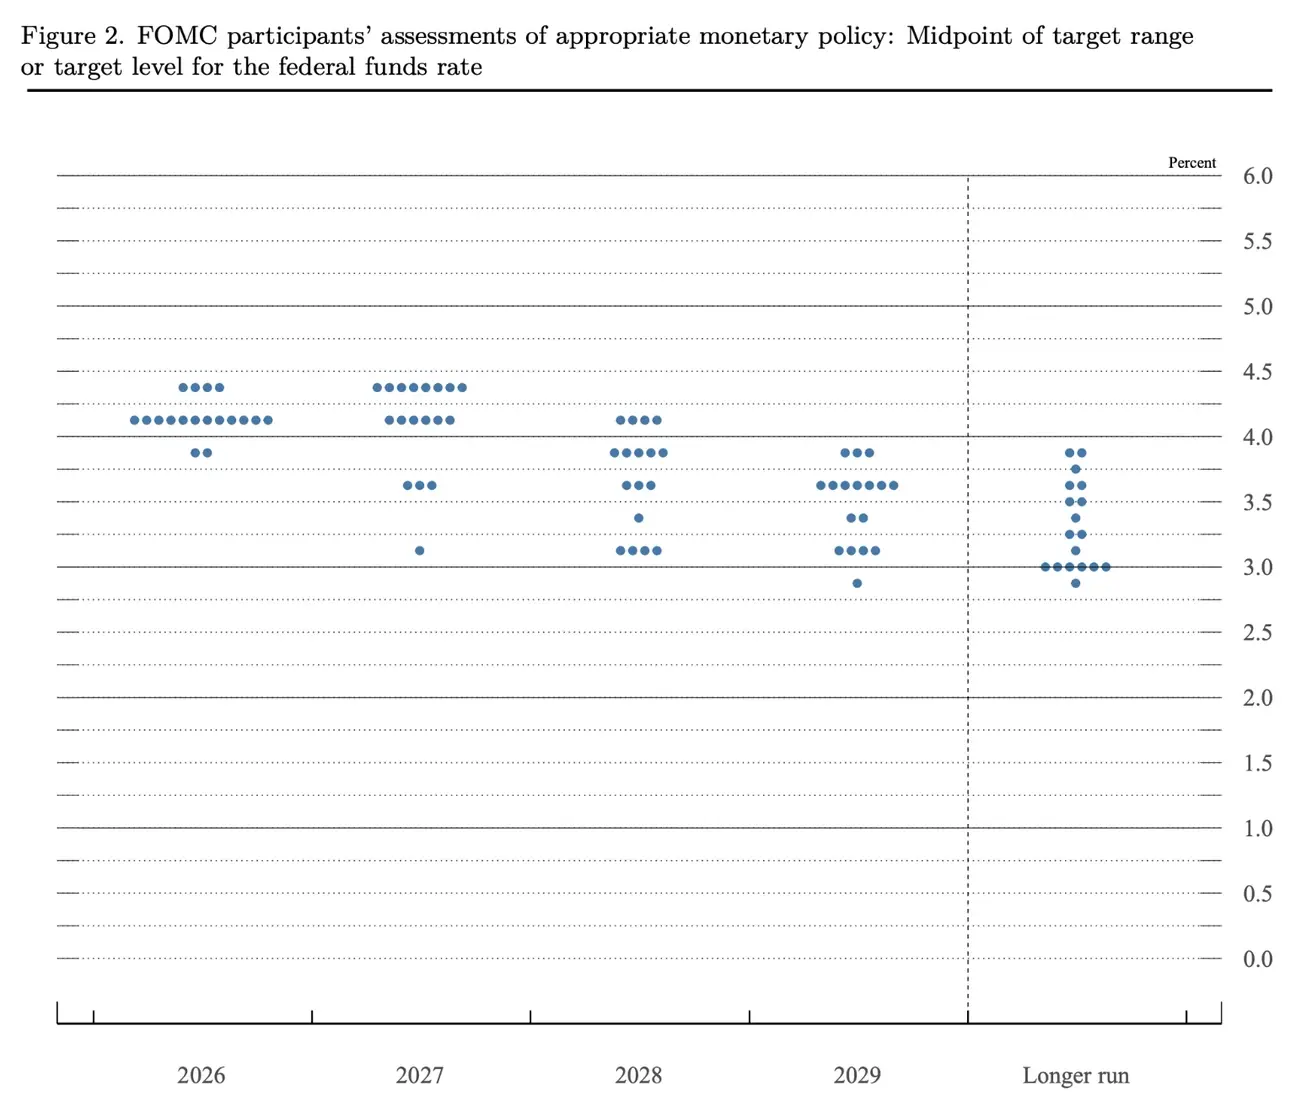
The median federal funds rate forecast implies a level of 4.1% (an additional +0.25%) through the end of 2027. Long-term forecast range: 3.00–3.50%.
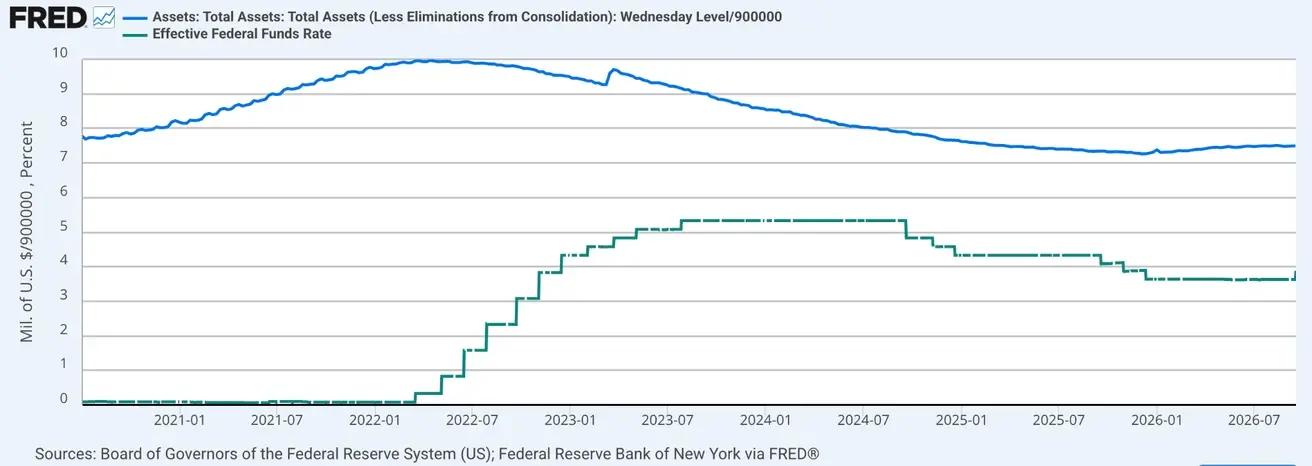
Federal Reserve Balance Sheet: $6.746 trillion, +3.23% since the suspension of quantitative tightening (QT), when the balance sheet stood at $6.535 trillion.
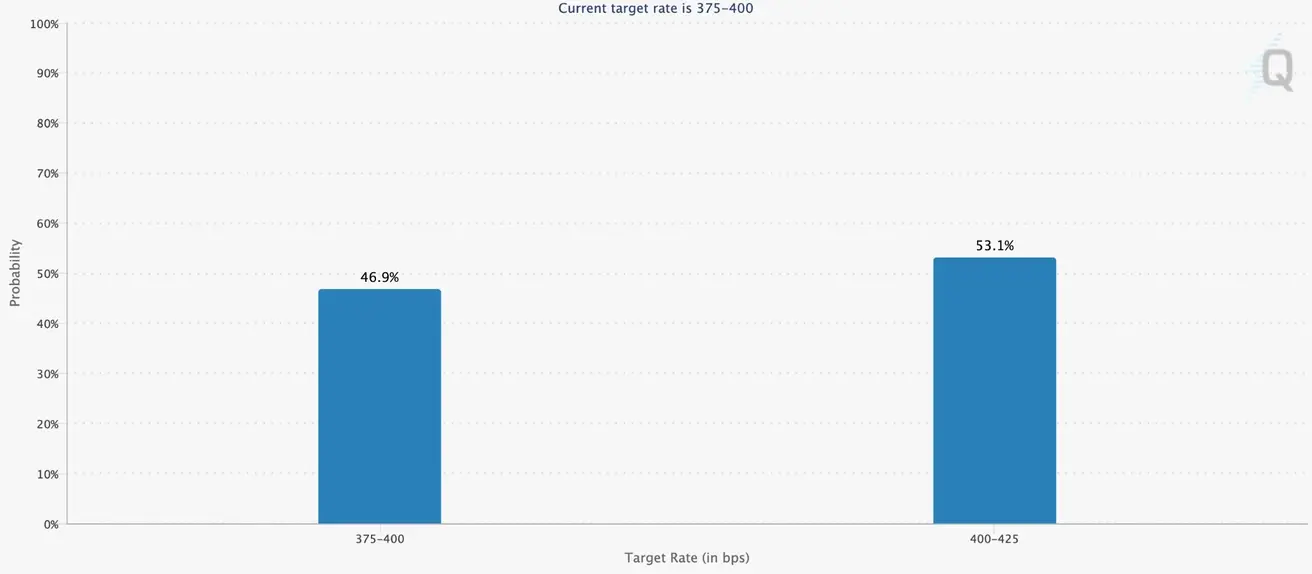
Market Forecast for Rate (FedWatch)
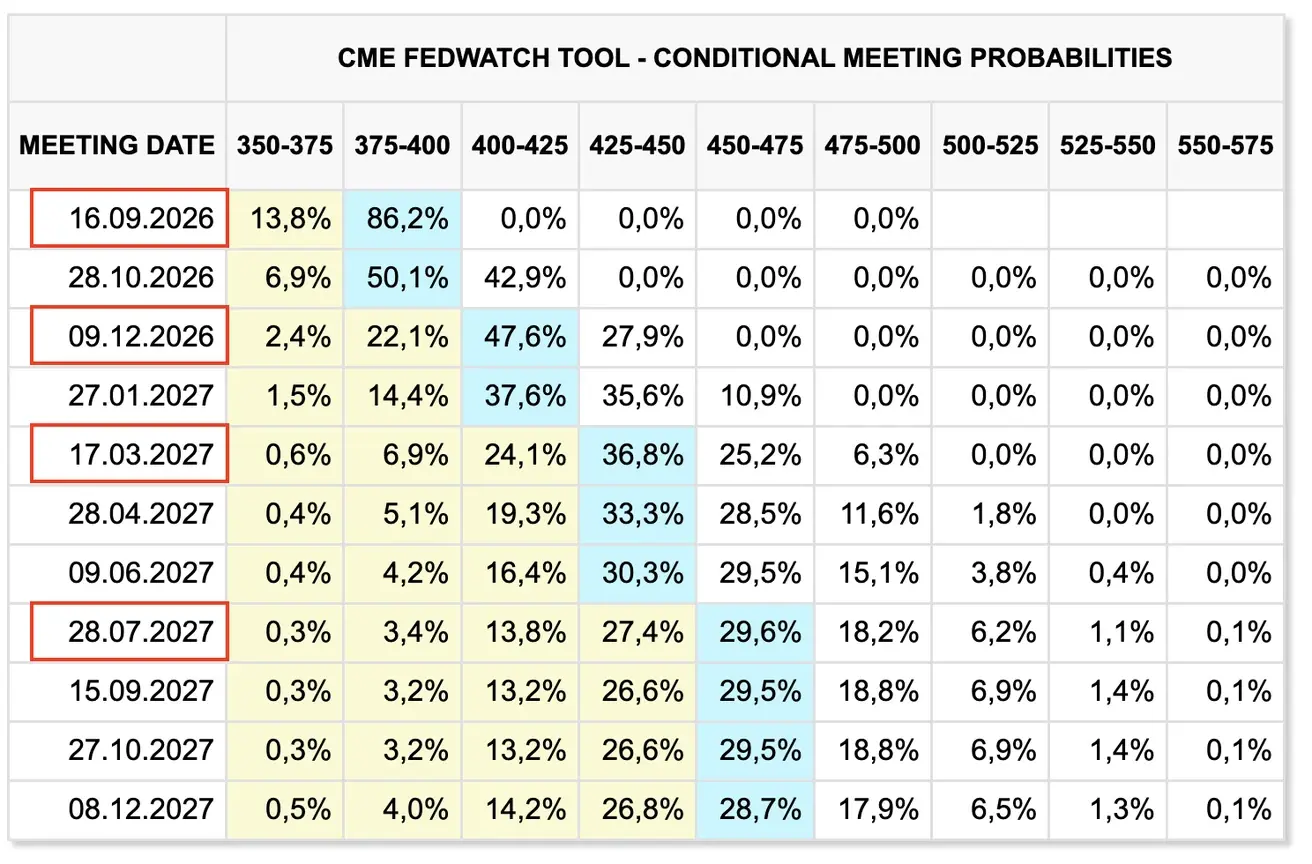
For the next FOMC meeting (October 28) - the estimated probability of a 0.25% rate hike is 53.1%:
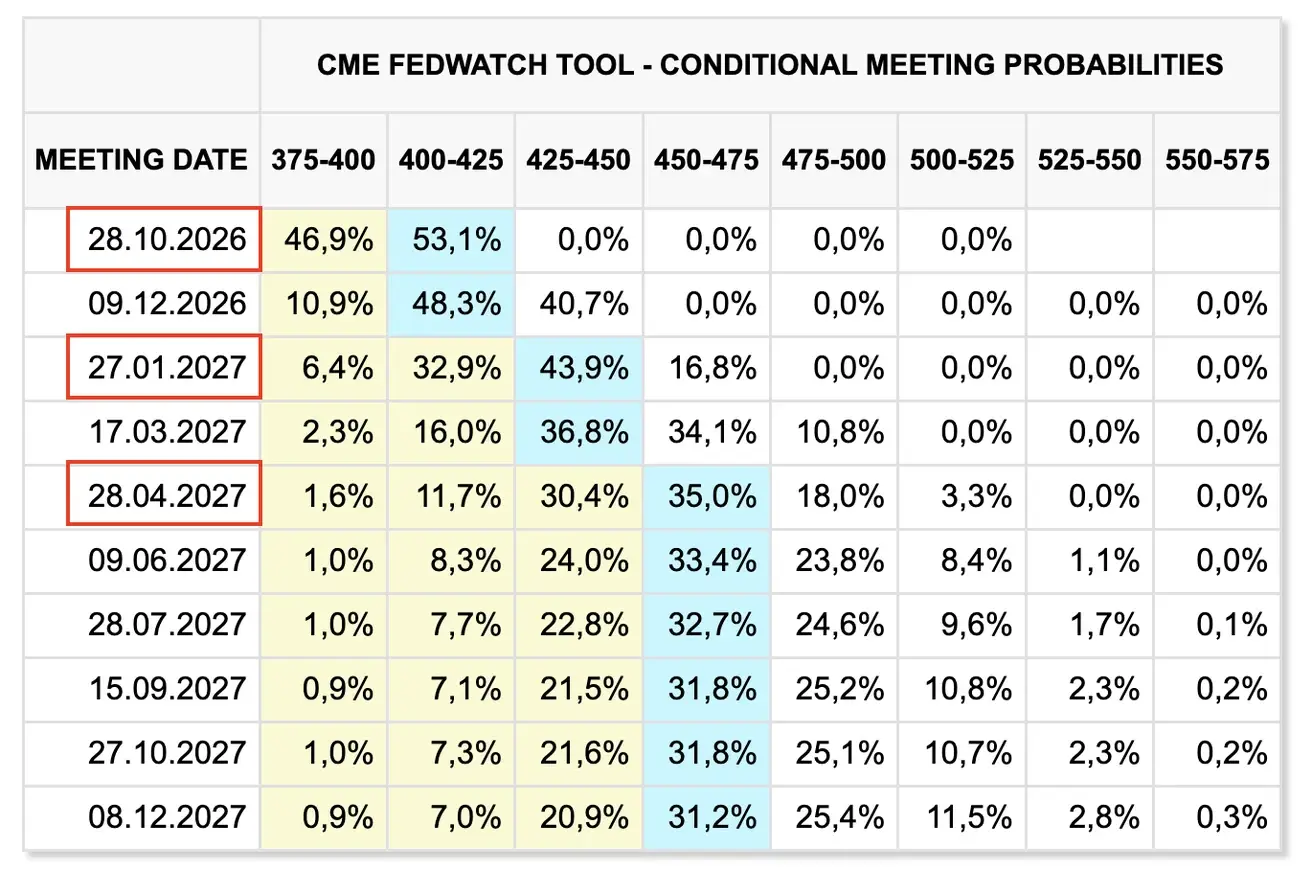
Over the next 12 months, the market continues to expect three 25-basis-point rate hikes to a range of 4.50–4.75%, with the final hike expected in April 2027:
Today:
A week earlier:
Bond Market
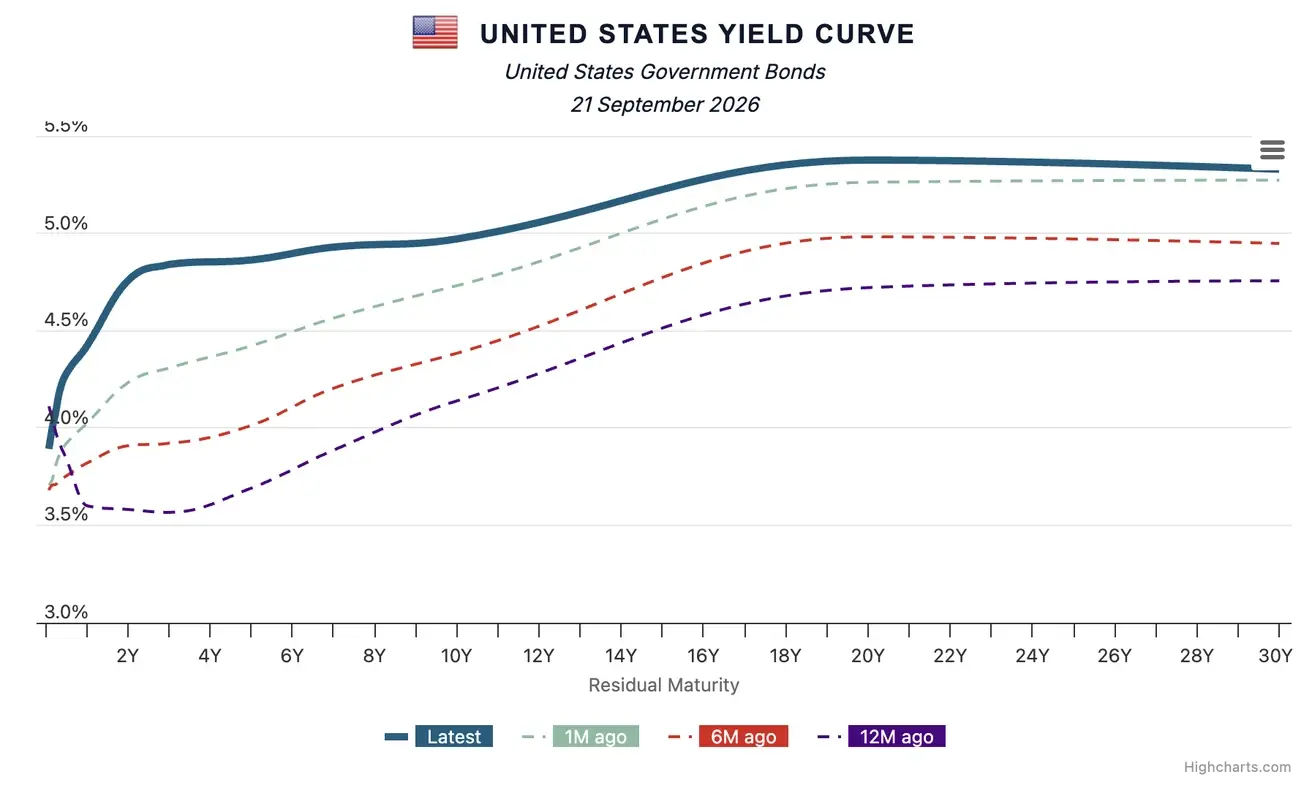
U.S. bond market — yields rose on the short/medium end of the curve while 30-year yields declined.
U.S. Treasury Bonds 20+ Years (TLT ETF): +0,47% (week close: 81,25); year-to-date: -6.78%
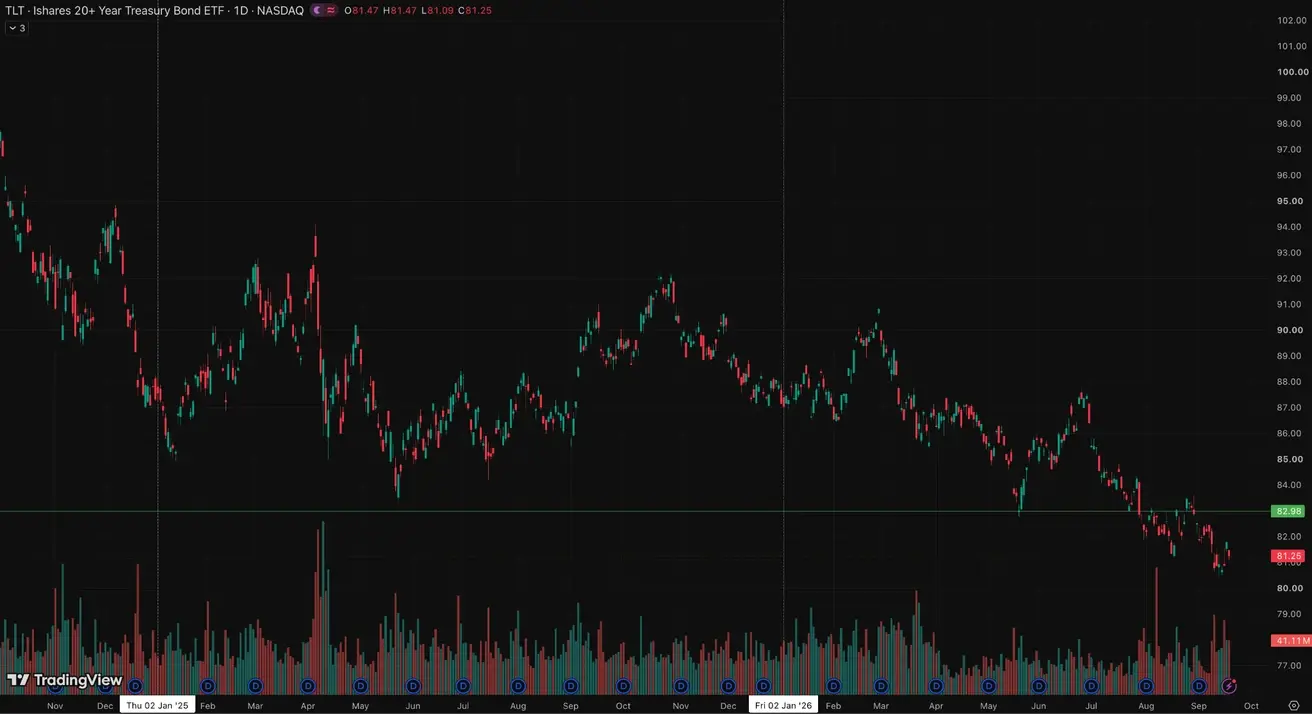
Long-dated Treasuries reflect growing confidence in the Fed's decisively anti-inflationary stance. Short-term yields remained under upward pressure after the rate hike, while long-term yields moved lower. This can be read as: policy has become tighter today, but the probability of high inflation becoming entrenched for years has edged lower.
Yields and Spreads
- Market Yield on U.S. Treasury Securities at 10-Year Constant Maturity: 4.97% (previous: 4.98%);
- 2-Year U.S. Treasury Yield: 4.76% (previous: 4.63%);
- ICE BofA BBB US Corporate Index Effective Yield: 5.84% (previous: 5.86%).
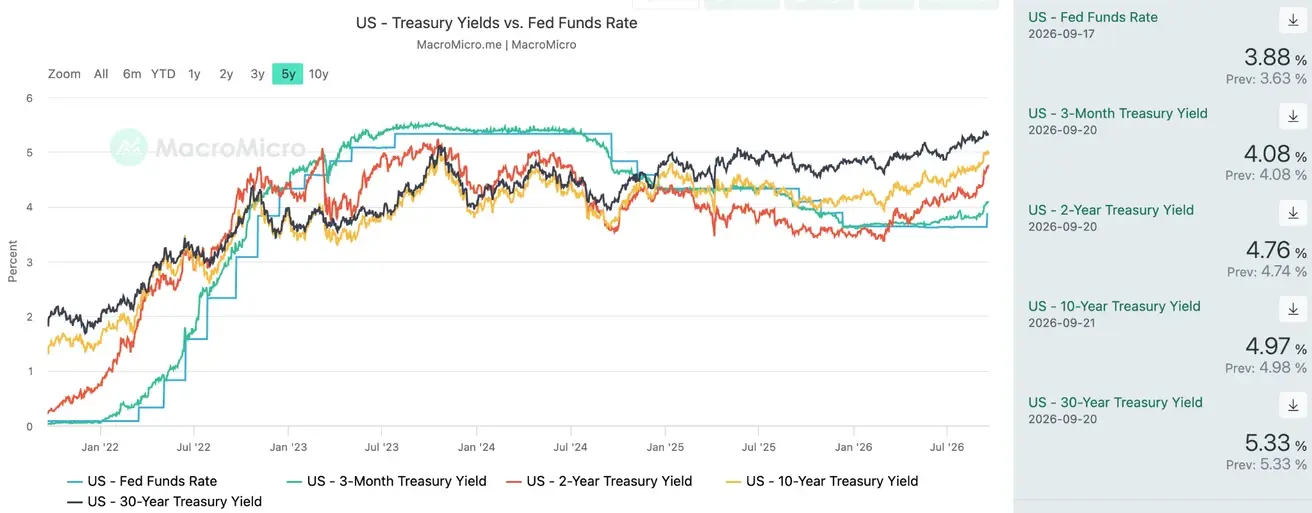
- The yield spread between 10-year and 2-year U.S. Treasury securities stands at 21 basis points (previous: 35 bps);
- The yield spread between 10-year and 3-month U.S. Treasury securities stands at 89 basis points (previous: 96 bps).
U.S. Treasury Yield Curve
The cost of a 5-year U.S. Credit Default Swap (CDS) — a market-based measure of sovereign default insurance — is 32.39 basis points, compared with 32.95 basis points a week earlier.
Equity Market
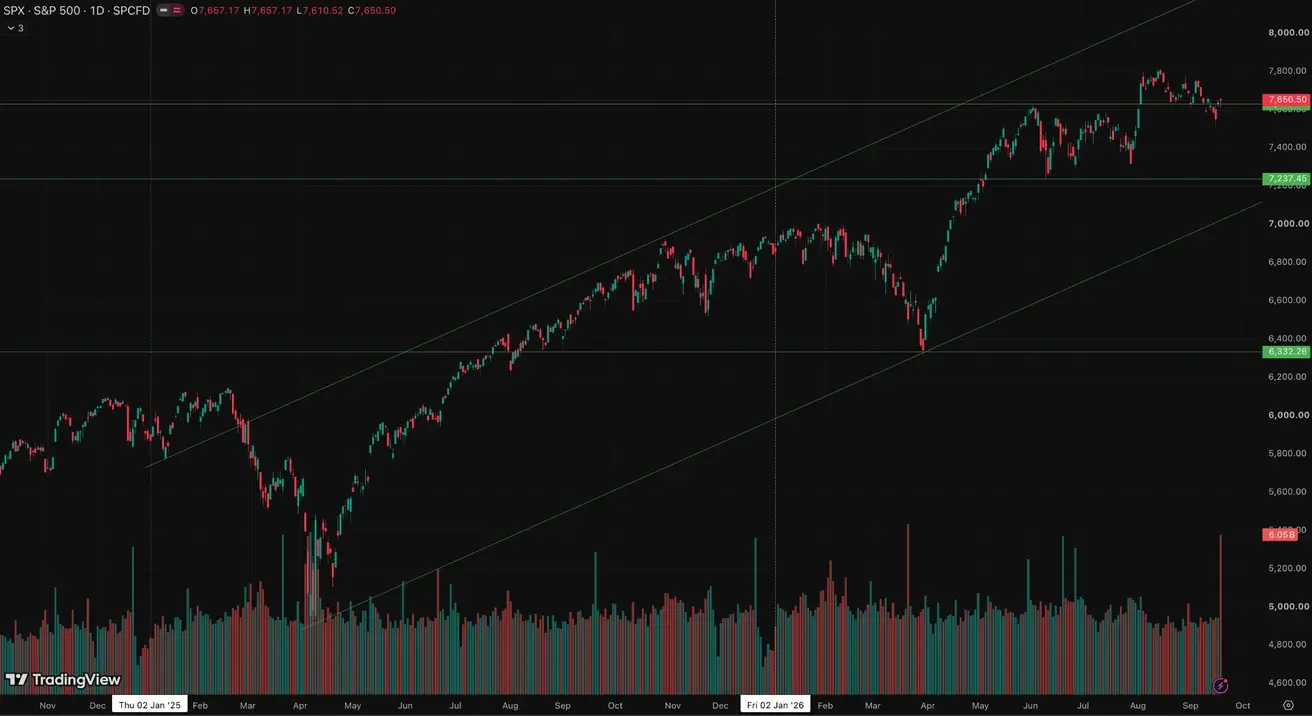
Following Warsh's press conference, the market initially read the meeting as more hawkish than expected. But by now, the entire sell-off has been bought back, and the market likely concluded the rhetoric was tougher than the actual policy trajectory - more verbal intervention than future action. The main risk remains energy prices.
SP500
Weekly performance: -0,08% (week-end close: 7650,50); year-to-date: +11,76%.
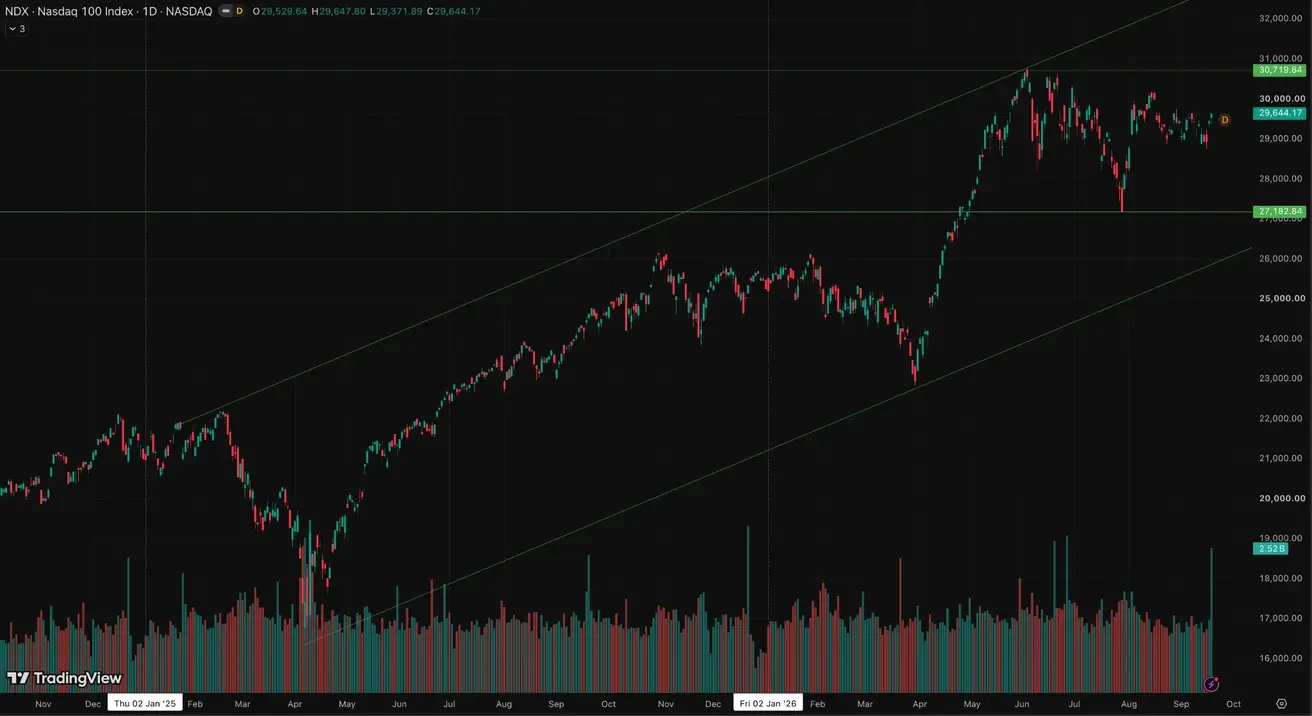
NASDAQ100
Weekly performance: +0,94% (week-end close: 29644,17); year-to-date: +17,40%.
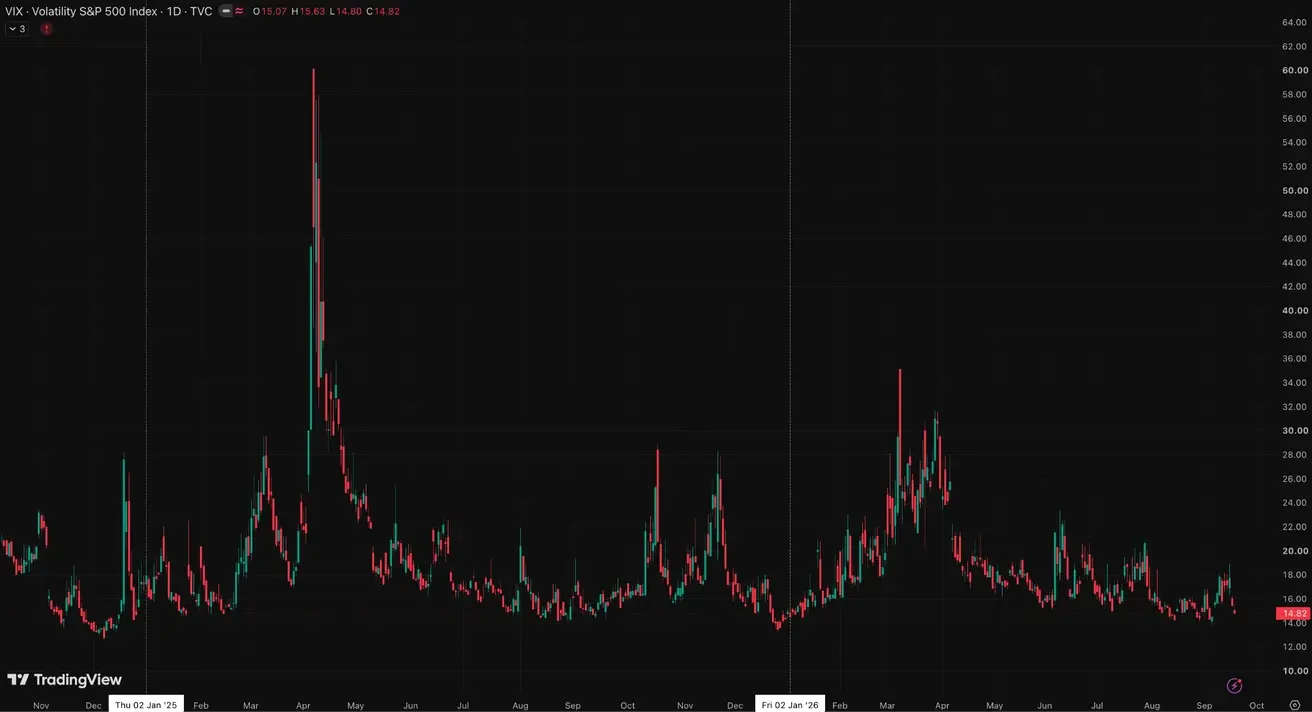
VIX
VIX (volatility index): week-end close at 14,82 points.
Wells Fargo lowered its year-end 2026 S&P 500 target to 7,700 from 7,950.
Eurozone
- The ECB raised interest rates, while maintaining a hawkish stance as inflationary risks continue to increase;
- Against the backdrop of the conflict in the Middle East, the ECB revised its GDP forecasts downward and raised its inflation projections for the coming years.
Macroeconomic Data
Interest Rates
- Deposit Facility Rate: 2.5% (previous: 2.25%);
- Marginal Lending Facility Rate: 2.9% (previous: 2.65%) — the rate at which banks can obtain overnight funding from the central bank;
- Main Refinancing Rate (Policy Rate): 2.65% (previous: 2.40%).
Inflation: Consumer Price Index (CPI) (August)
- Core CPI (YoY): 2.4% (previous: 2.5%);
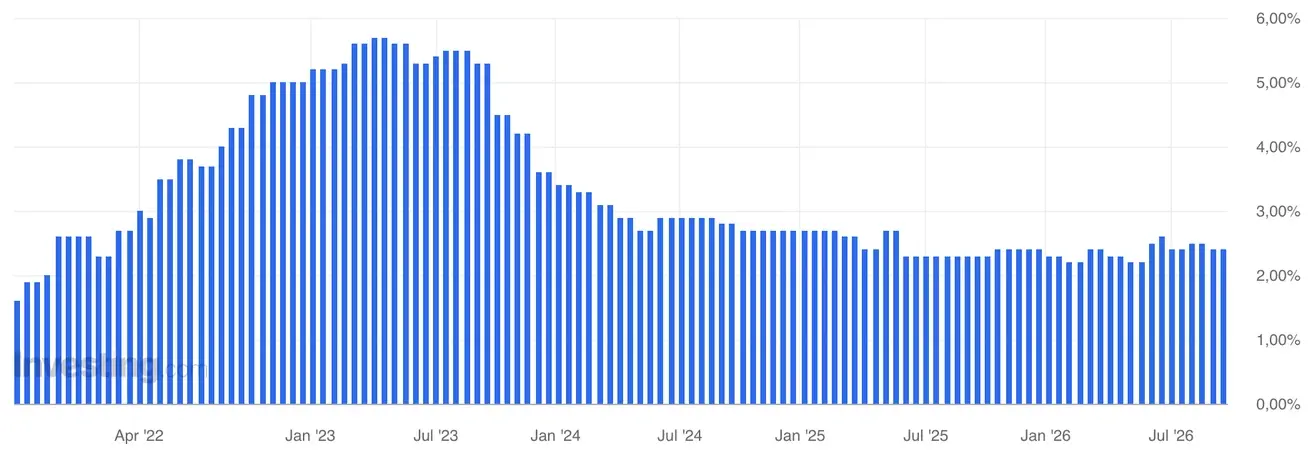
- Headline CPI: revised from 2.9% to 0.4% (MoM) (previous: 0.2%);
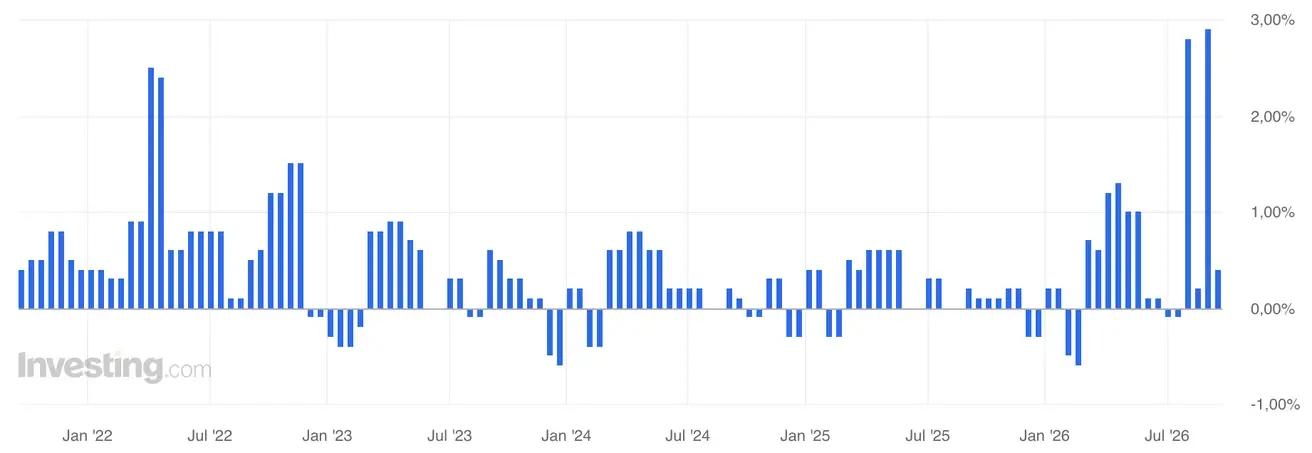
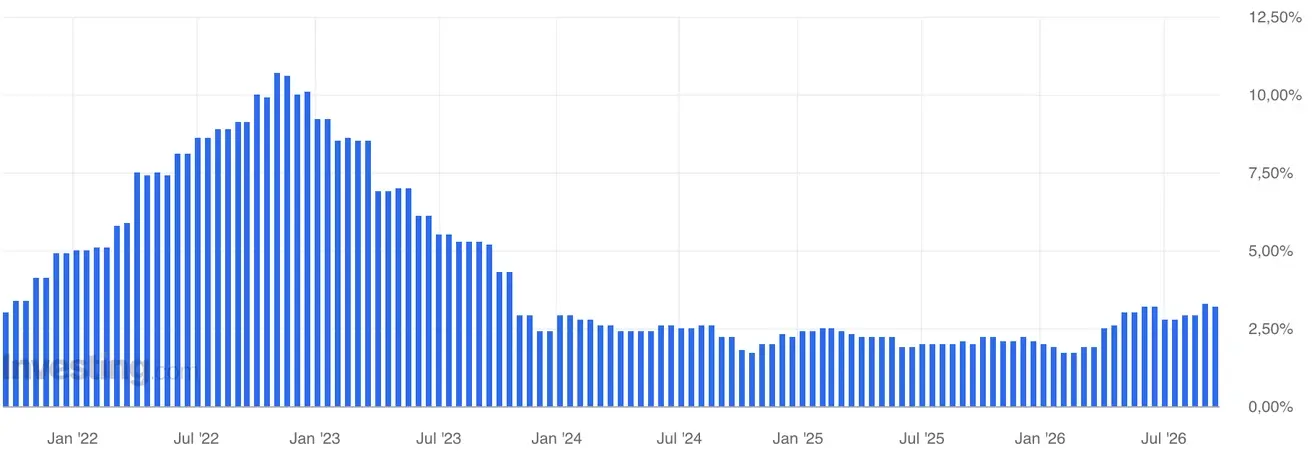
- CPI: 3.2% (YoY) (previous: 2.9%).
Inflation Expectations (August)
- 1-year expectations: 3.0% (previous: 2.9%).
- 3-year expectations: 2.9% (previous: 2.7%).
GDP (Q2 2026)
- QoQ: 0.6% (previous: -0.2%);
- YoY: 0.5% (preliminary estimate: 0.4%); (previous: 0.3%).
Unemployment Rate (August)
- 6.4% (previous: 6.3%).
Industrial Production (August)
- MoM: -0.1% (previous: 0.0%);
- YoY: 1.67% (previous: 1.37%).
Purchasing Managers’ Index (PMI) (August)
- Services PMI: 51.6 (previous: 51.7);
- Manufacturing PMI: 52.7 (previous: 52.8);
- S&P Global Composite PMI: 52.0 (previous: 52.0).
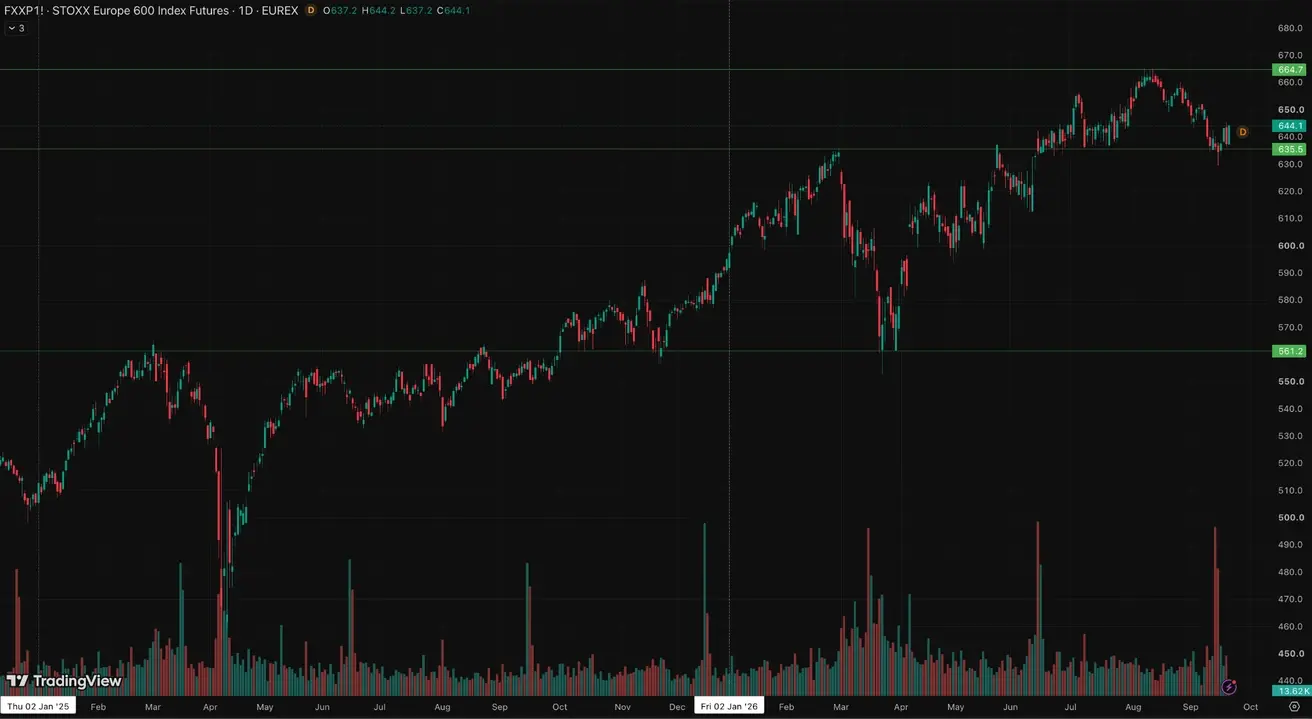
Euro Stoxx 600 (FXXP1!)
Weekly performance: +0,22% (week-end close: 640,8); year-to-date: +7,88%.
China
China’s economy continues to stabilize, supported by strong exports, while domestic demand and investment gradually recover. Policymakers remain measured and targeted in their approach to economic stimulus.
- Interest rates remain unchanged;
- Monetary policy remains accommodative;
- China reaffirmed its commitment to fiscal support for economic growth under its 2026 plan, including measures to stimulate domestic demand, optimize tax incentives and subsidies, and modernize industrial capacity.
Macroeconomic Data
Interest Rates
- 1-Year Loan Prime Rate (medium-term lending): 3.00%;
- 5-Year Loan Prime Rate (benchmark for mortgage lending): 3.50%.
Inflation Indicators (August)
- Consumer Price Index (CPI): 0.4% MoM (previous: -0.1%); 0.8% YoY (previous: 0.5%):
- Producer Price Index (PPI): 3.8% YoY (previous: 3.5%).
Trade Data
- Imports (August): 28.2% YoY (previous: 27.5%);
- Exports (August): 25.0% YoY (previous: 23.9%);
- Trade Balance (USD) (August, YoY): $119.9 billion (previous: $112.5 billion).
GDP (Q2 2026)
- QoQ: 0.9% (previous: 1.3%);
- YoY: 4.3% (previous: 5.0%).
This is below the target trajectory and reflects weaker domestic momentum.
Labor Market
- Unemployment Rate (August): 5.3% (previous: 5.2%).
Industrial Activity
- Industrial Production (July, YoY): 5.2% (previous: 4.5%).
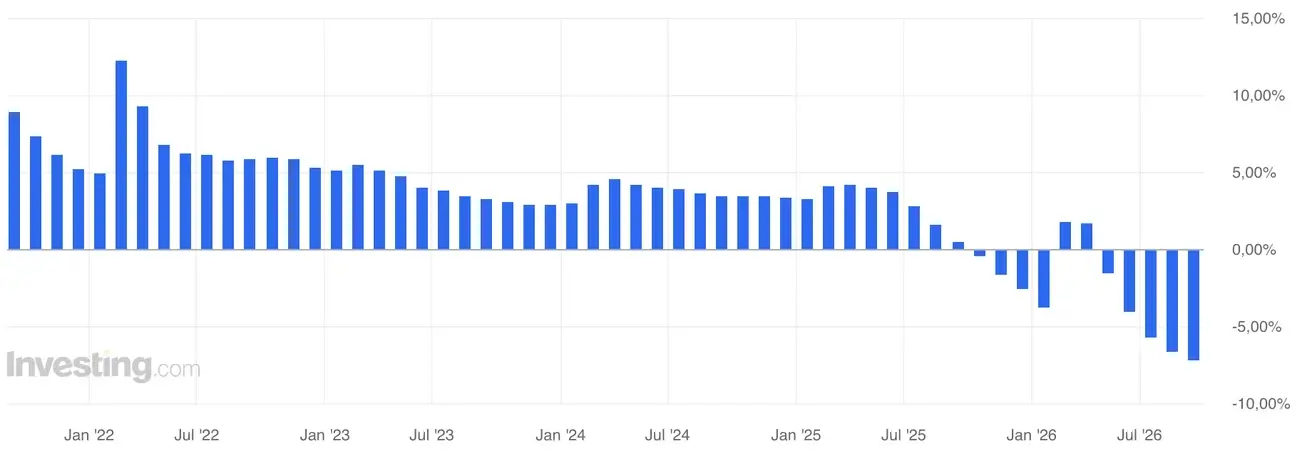
Fixed Asset Investment
- June, YoY: -7.2% (previous: -6.7%).
Retail Sales
- July, YoY: 0.6% (previous: 0.9%).
Purchasing Managers’ Indices (PMI) (August)
- Manufacturing PMI: 49.8 (previous: 49.2);
- Non-Manufacturing PMI: 49.0 (previous: 49.0);
- Composite PMI: 49.5 (previous: 49.3).
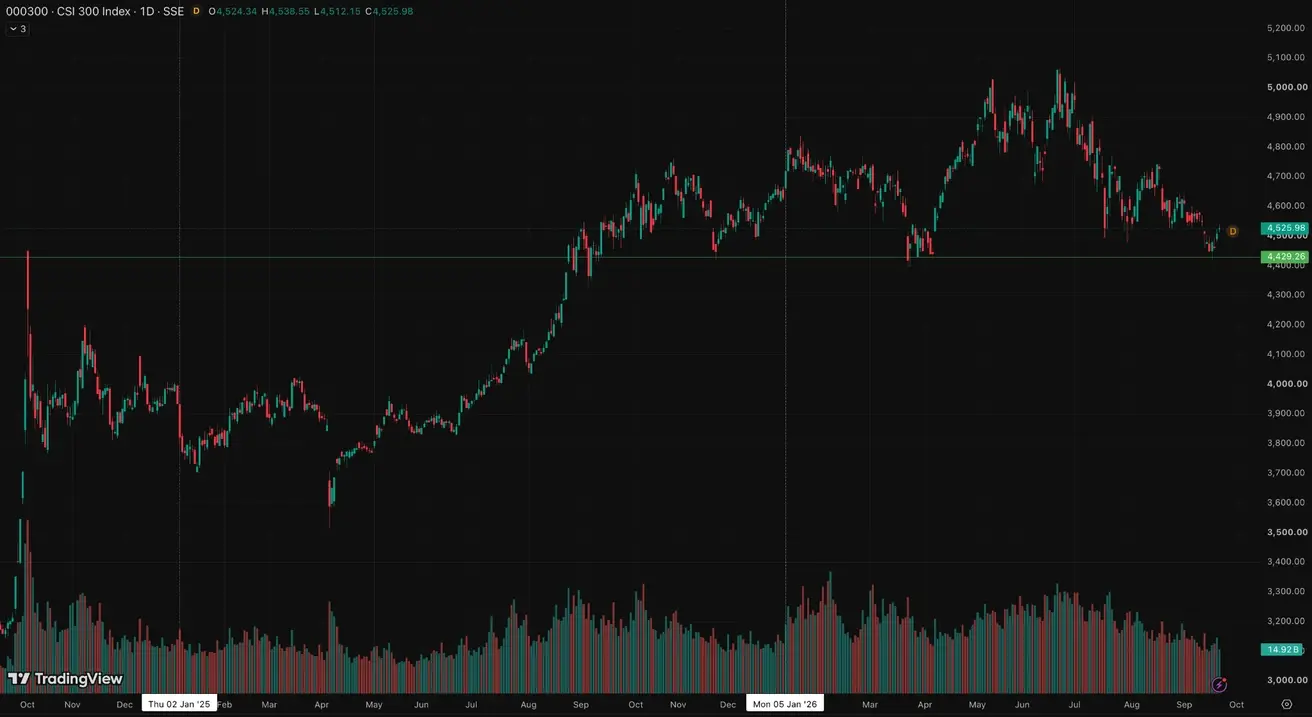
CSI 300 Index (000300.HK)
Weekly performance: -0,06% (week-end close: 4525,98); year-to-date: -3,31%.
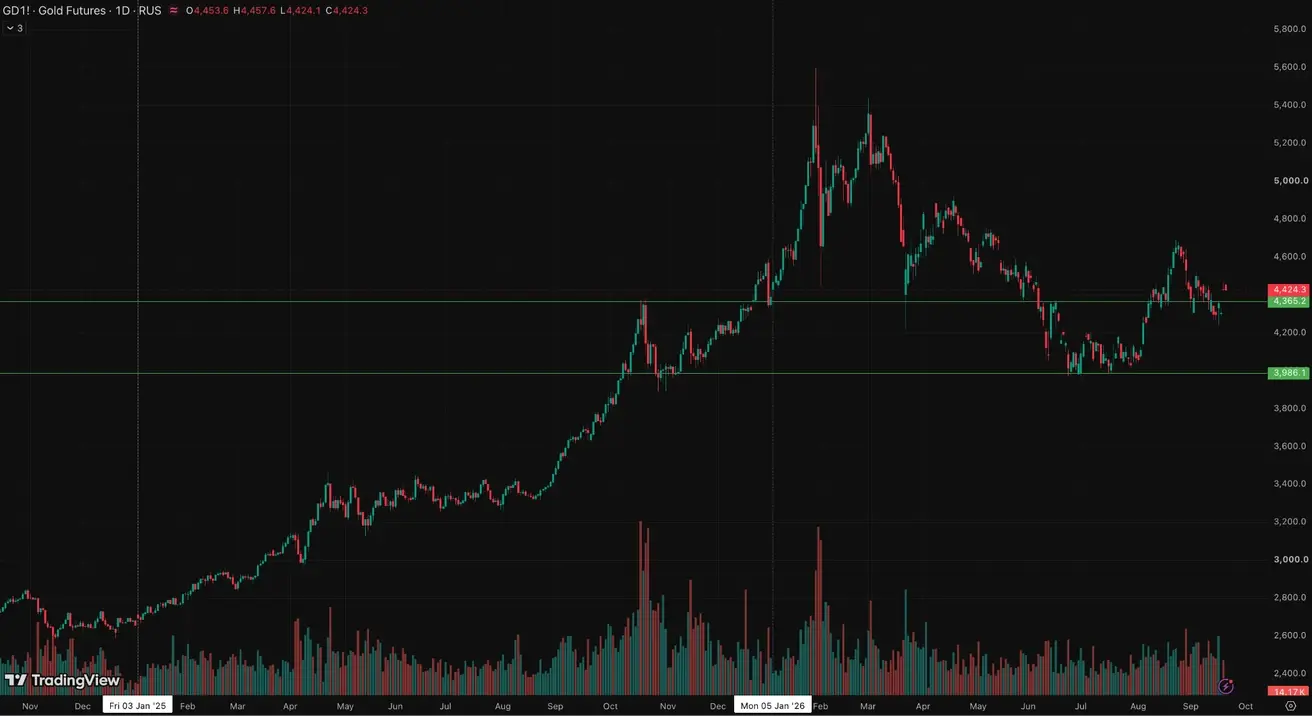
Gold Futures (GC)
Weekly performance: +1,25% (week close: $4428,2 per troy oz); year-to-date: +2,22%
Oil Futures
Weekly performance: -3,97% (week close: $96,08 per barrel); year-to-date: +67,36%
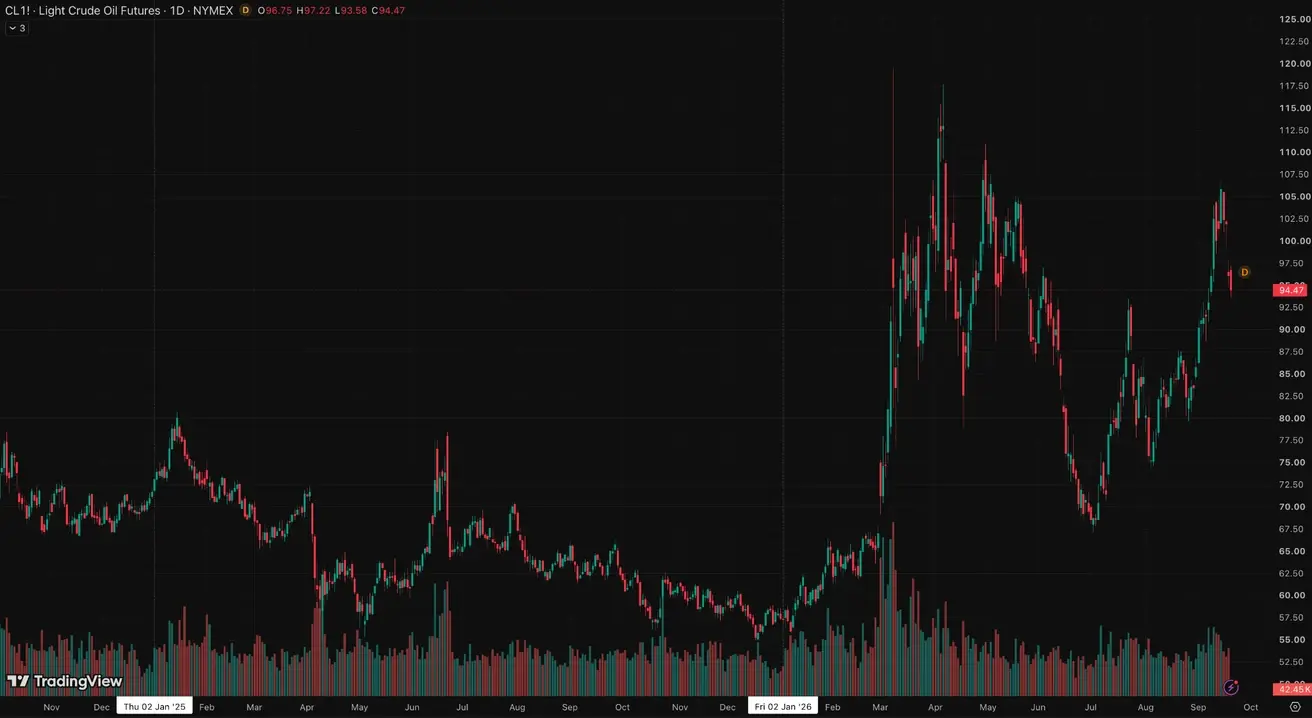
Oil fell about 4% as supply concerns eased, in particular around Saudi crude flows moving through Oman. For the market, this naturally lowers inflation concerns and reduces the need for an even more aggressive central bank response.
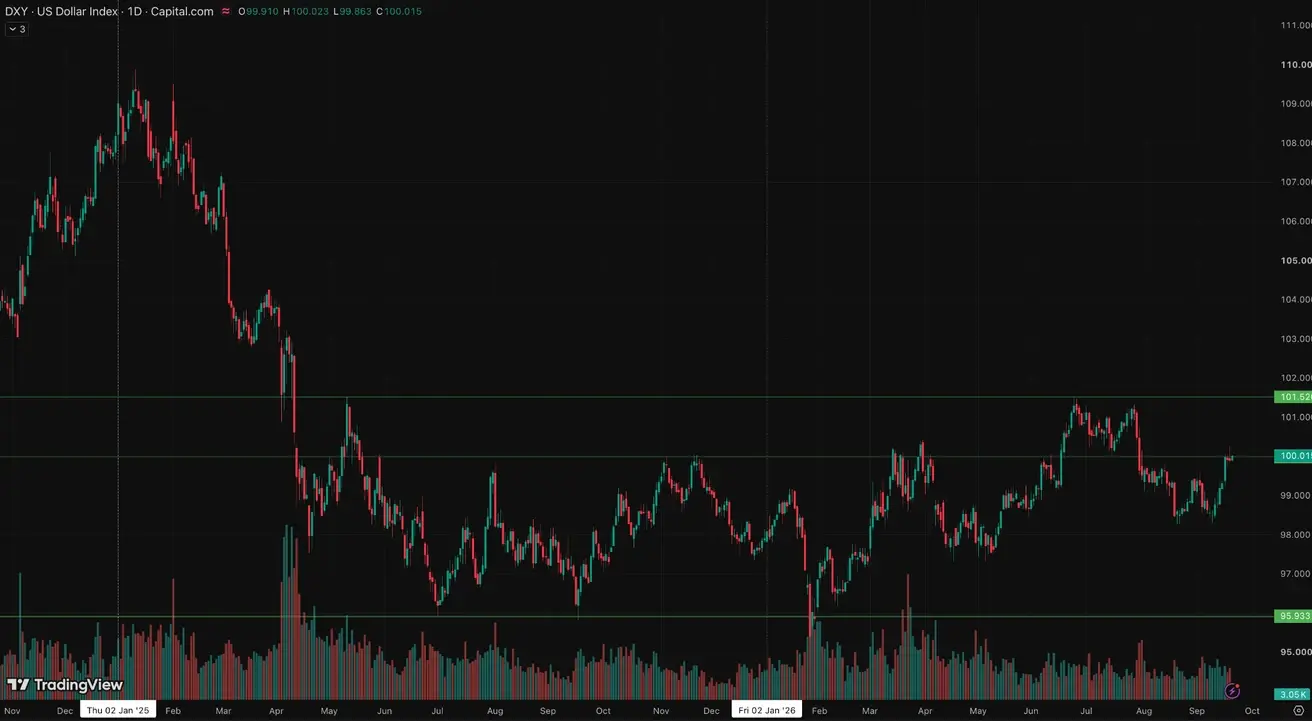
Dollar Index Futures (DX)
Weekly performance: +1,10% (week close: 99,895); year-to-date: +1,94%.
Crypto Market
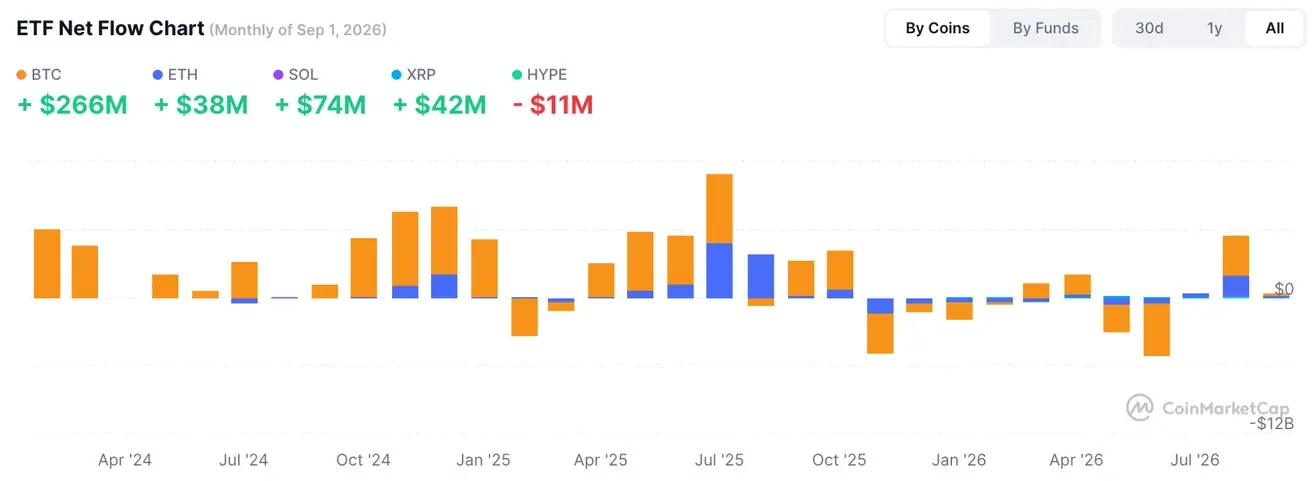
The CLARITY Act failed a key Senate vote on September 15 and has not been passed at this stage. The Senate voted not on final passage of the bill, but on ending debate and moving to substantive consideration. That required 60 votes, but the result was 49 in favor, 50 against, and one senator not voting. In short, the Senate did not even move on to substantive consideration of the bill.
That said, the procedural option of a repeat vote was preserved. To use it, Republicans will need to resume negotiations and find at least 11 more votes. The main sticking points remain ethics restrictions, conflicts of interest around administration officials' crypto holdings, and separate questions over stablecoin regulation and regulators' authority.
The head of the CFTC (Commodity Futures Trading Commission) said the agency is ready to introduce crypto rules despite the failed procedural vote on the CLARITY Act in the Senate. SEC Chair Atkins, following the CFTC head, likewise said the SEC would put forward its own crypto rules. This rhetoric supported the crypto market.
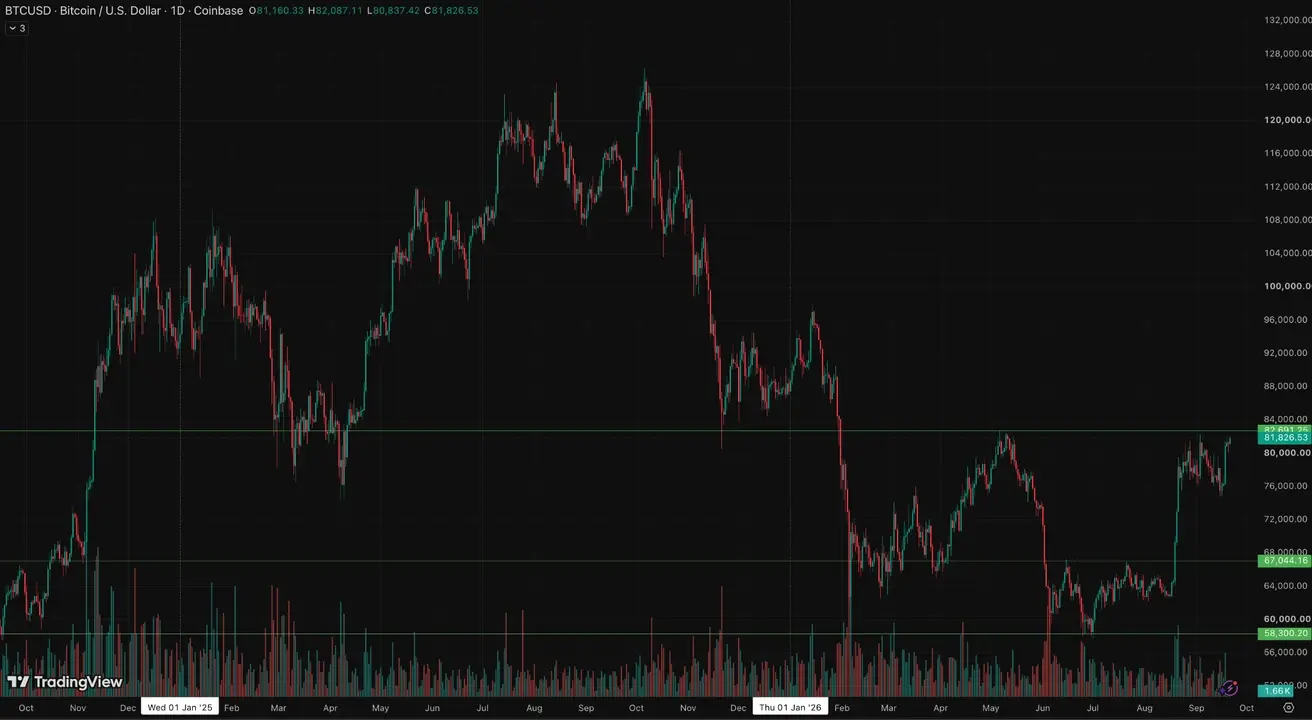
BTC Futures
Weekly performance: +5,68% (week close: $81,159.64); year-to-date: -7,48%.
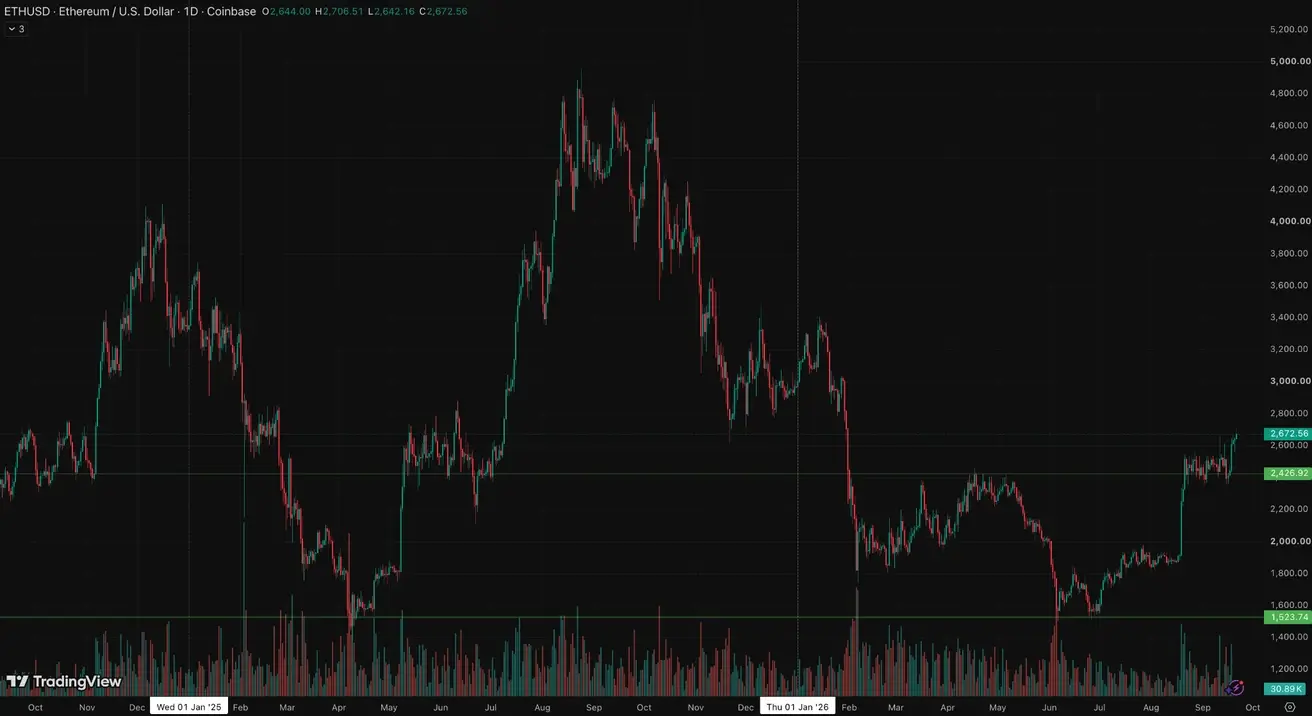
ETH Futures
Weekly performance: +6,80% (week close: $2644,31); year-to-date: -11,08%.
Total Cryptocurrency Market Capitalization
Total crypto market capitalization: $2,87 trillion (vs $2,66 trillion a week earlier) (coinmarketcap.com).
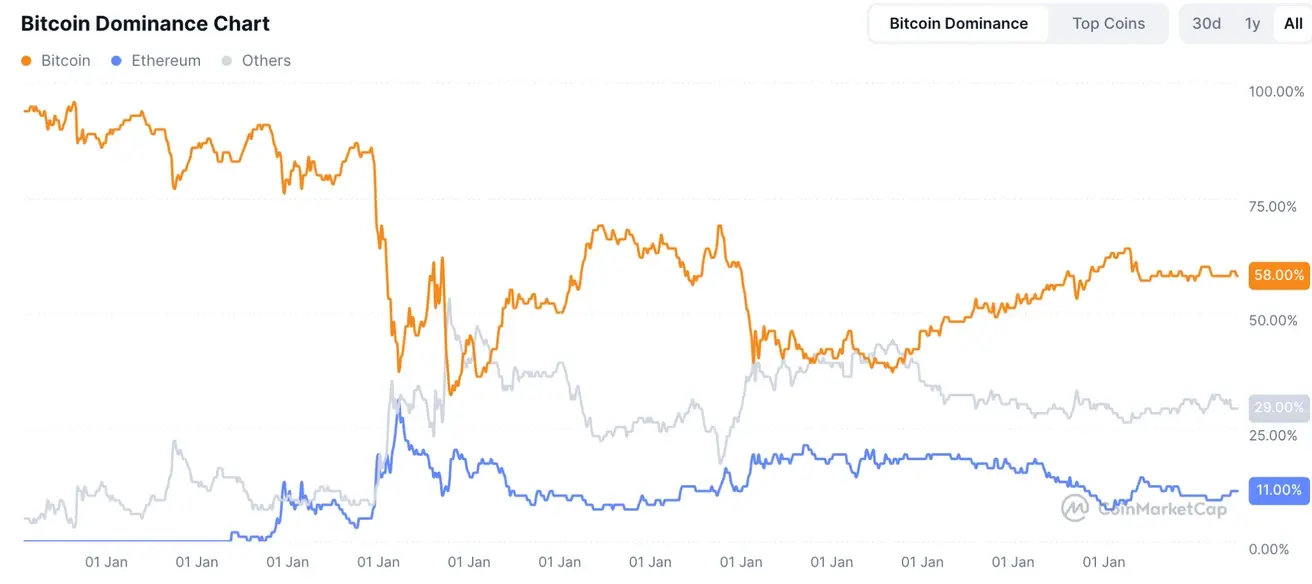
Crypto asset market shares:
- Bitcoin 58,9% (prev. (58,9%)
- Ethereum 11,5% (prev. 11,6%)
- Others 29,6% (prev. 29,5%)